
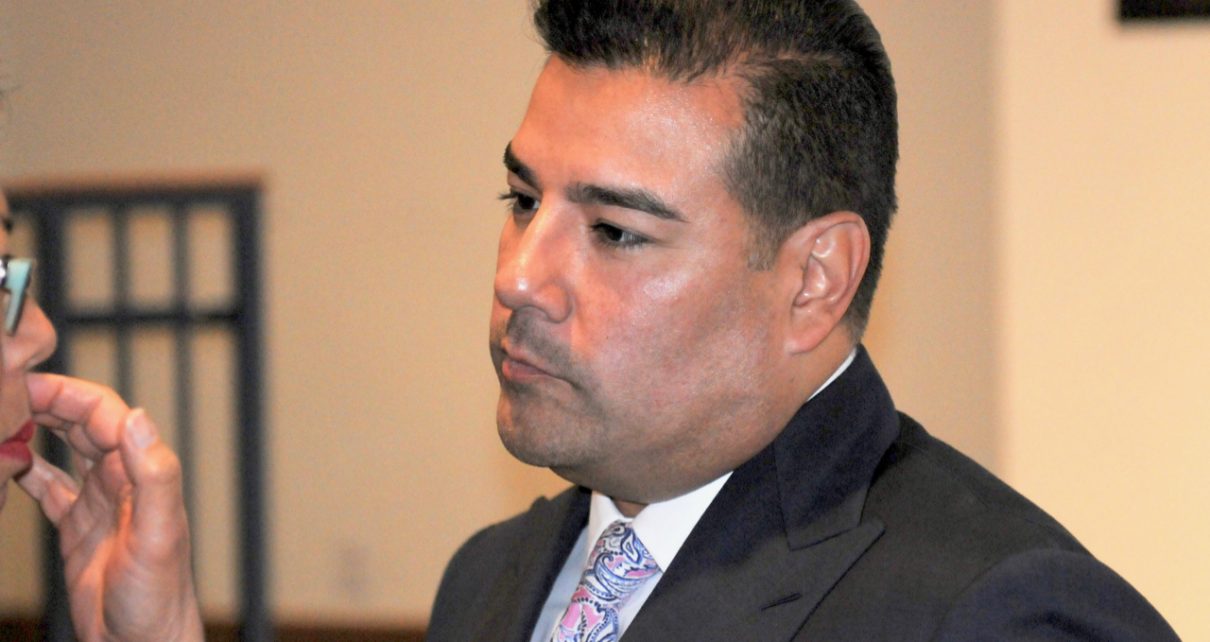
Insurance Commissioner Ricardo Lara. (Photo: Kevin Sanders for California Globe)
California Judge Sues Insurance Commish For Firing After Ruling Against Insurer Settlements
Ffter living like a rock star for 8 years on the taxpayers’ dime, Ricardo Lara should be prosecuted
By Katy Grimes, November 11, 2026 4:38 pm
Former California Department of Insurance Chief Administrative Law Judge Kristin Rosi has sued Insurance Commissioner Ricardo Lara and others, alleging she was fired for challenging illegal approvals of insurance rate hikes and that officials undermined administrative law judges’ authority.
Calmatters first reported:
Kristin Rosi, former chief administrative law judge for the department, filed the lawsuit in Alameda County Superior Court in late September. She alleges that Lucy Wang — the former special counsel who was also a deputy insurance commissioner — and other top officials at the department retaliated against her for calling out their practices and refusing to comply with orders to revoke or change her rulings.
“The California Department of Insurance has spent much of 2026 approving rate increases for homeowners and auto insurers under Commissioner Ricardo Lara’s Sustainable Insurance Strategy,” Insurancebusinessmag.com reports. “A lawsuit filed by the department’s former chief administrative law judge now alleges that the approval process behind some of those increases bypassed the independent judicial oversight that state law requires.”
What’s this all about?
Rosi claims the department routinely approved home and auto rate increases through negotiated settlements with insurers and consumer groups, bypassing required review by the Administrative Hearing Bureau’s ALJs and public hearings mandated by Proposition 103.
Prop 103 gives the commissioner authority to review rates for auto, home, and other lines, requires public hearings for increases of 7% or more, and bars premiums that are excessive, inadequate, unfairly discriminatory, or otherwise unlawful. When a consumer group formally requests a hearing on a proposed increase, the department is required to hold one before approving the rate.
As Stacy Korsgaden, former candidate for Insurance Commissioner, explained:
In 1988, California reached a fork in the road. Voters passed Proposition 103, ushering in a regime of government micromanagement disguised as consumer advocacy. Price controls. Profit controls. Risk management dictated by Sacramento bureaucrats and career activists. And at the helm? An elected Insurance Commissioner, focused on politics, not the policyholders.
This wasn’t just regulation. It was socialism.
Under this system, the Client—the person insurance is meant to protect—has suffered the most. Fewer choices, higher premiums, and weakened competition have resulted, and insurance providers are struggling to survive. The results are predictable when you smother the free market and vilify profit.
In October 2024, while ruling on consumer group compensation requests, Kristin Rosi found the department was approving rate requests without following proper procedures. She alleges this exposed a pattern of using uncodified “prior rate approval procedures.” After her rulings, she says officials, including former special counsel and deputy commissioner Lucy Wang, retaliated by trying to limit ALJs’ jurisdiction, pressuring her to change or revoke rulings, and stripping authority from the judicial branch. The suit quotes Lara emailing her to “get on board” with a plan that would restrict judges to reviewing settlements only after a notice of hearing had been issued.
Rosi further alleges improper ex parte communications (e.g., officials meeting with the department’s legal team about pending matters without all parties), separation-of-powers violations within the department, whistleblower retaliation, sex discrimination, sexual orientation discrimination, and infliction of emotional distress.
Rosi also filed related California State Bar complaints against Wang and others.
What’s next?
Insurance Commissioner Lara is term-limited and on his way out of the door, but is leaving a disaster in his wake, after living like a rock star for 8 years on the taxpayers’ dime. He should be prosecuted.
Jane Kim was elected the next insurance commissioner and will take office in January. She said she is committed to transparency and accountability and plans to investigate the claims upon taking office. The first case management conference in the lawsuit is scheduled for February 16, 2027.
California’s property insurance market deteriorated substantially during Ricardo Lara’s two terms (2019–January 2027), and he leaves a mountain of problems and a mess for Kim to deal with.
- Massive growth in the FAIR Plan, the state’s last-resort insurer. It expanded from roughly 124,000 policies around the start of his tenure to over 645,000 by late 2025, with exposure rising into the hundreds of billions of dollars. Many January 2025 Los Angeles wildfire victims were left underinsured or relying on minimal FAIR Plan coverage.
- Insurer retreat and non-renewals: Major carriers restricted new policies, dropped customers, especially in wildfire-prone areas, and limited coverage. Premiums rose sharply—reports cited increases of around 23% since 2023 in some analyses, with larger cumulative jumps earlier in the period.
- Delayed and contested reforms: Lara’s “Sustainable Insurance Strategy” (finalized around 2024–2025) allowed catastrophe modeling for future risks, faster rate reviews, and inclusion of reinsurance costs in exchange for commitments to write more policies in higher-risk zones. Critics (including Consumer Watchdog, former commissioners Dave Jones and John Garamendi) argue the rules contain loopholes, that many approved rate hikes produced little or no new high-risk coverage, and that earlier inaction allowed the crisis to deepen.
- Ethics and transparency issues: Early acceptance of insurance-industry-related campaign contributions, extensive international travel to far-away places like Paris, Singapore, Dubai, and Bermuda, often involving first-class or business-class travel and five-star hotels, with incomplete disclosure of funding sources such as the industry-linked National Association of Insurance Commissioners), and open FPPC investigations into travel gifts and campaign expenses.
As we reported in “48 Global Trips for CA Insurance Commish Ricardo Lara as Insurance Carriers Were Leaving California,” “California’s elusive Insurance Commissioner Ricardo Lara has built up a lot of frequent flyer miles while California homeowners have been getting hit with massive spikes in insurance premiums, or getting notices that their insurance is cancelled altogether, leaving only double or triple rate increases in the government’s last-resort FAIR insurance plan.”
California’s insurance boss enjoyed safaris, limos, and 5-star resorts, paid for by California taxpayers.
Hopefully, Jane Kim doesn’t catch the travel bug upon taking office.

A California native and Navy mom, Katy lives in Sacramento, CA.
- California Judge Sues Insurance Commish For Firing After Ruling Against Insurer Settlements - November 11, 2026
- PLF Lawsuit: California Legislature Tries to Cover Up Communications with Coastal Commission - November 11, 2026
- The Top 10 presidents With the Biggest Midterm Losses - November 10, 2026
RELATED ARTICLES
-
-
August 2, 2019
-
 September 16, 2024