
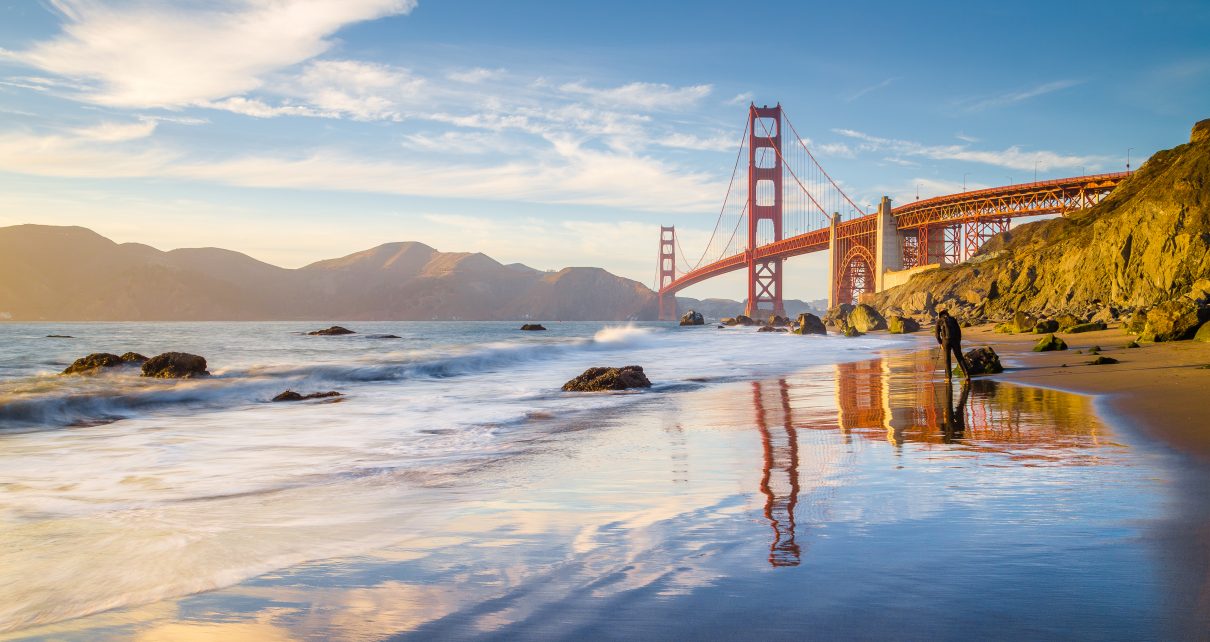
Panoramic view of famous Golden Gate Bridge from scenic Baker Beach, San Francisco, CA. (Photo: canadastock/Shutterstock)
For Sales Tax Rates, How High is Too High?
If both Bay Area measures pass, residents of Pacifica will see their rate rise from 9.875% to an eye-popping 11.375%
By Marc Joffe, September 14, 2026 12:00 pm
California voters usually encounter sales-tax increases one at a time. A quarter-cent here, a half-cent there, perhaps a penny for a city facing a budget shortfall. Viewed individually, each increase can seem both modest and necessary. But after years of this process, sales-tax rates in much of the Bay Area are becoming exceptionally high.
This November provides a particularly striking example in the Bay Area. In addition to the Regional Transit Measure 0.5% sales tax, eight cities across the five RTM counties have placed their own sales taxes measures on the ballot. Voters in Clayton, Hercules and Pacifica will each consider 1.0% hikes. If both measures pass, residents of Pacifica will see their rate rise from 9.875% to an eye-popping 11.375%. Seven Alameda County cities including Oakland and Hayward will be close behind at 11.25%. But even these high tax Bay Area cities will be below Los Angeles County’s sales tax leaders, Palmdale and Lancaster, which will see 11.75% rates starting October 1.
Those numbers are high by national standards. The Tax Foundation calculates that the population-weighted average combined state and local sales-tax rate nationwide is 7.53%. California’s statewide rate alone is 7.25%, the highest in the country, before local add-ons.
California’s sales tax can also hit purchases that residents of some other states buy tax-free. Most clothing is taxable here, for example, while New Jersey exempts most clothing and footwear. And starting January 1, Californians will start paying sales tax on Microsoft 365, ChatGPT, and Claude subscriptions.
California law ostensibly contains a brake. Revenue and Taxation Code Section 7251.1 generally limits combined district transactions and use taxes within a county to 2%. Add that to the 7.25% statewide base rate and the normal ceiling is 9.25%.
But the state has repeatedly enacted special legislation allowing individual cities, counties and transportation agencies to exceed the limit. Senate Bill 63, which authorized this year’s Bay Area regional transit tax, explicitly provides that its tax does not count against the normal 2% ceiling. And last month. Gov. Gavin Newsom signed SB 762, authorizing thirteen jurisdictions around the state to exceed the limit.
Why does this keep happening? One driver is an economic problem that deserves more attention: Baumol’s Cost Disease.
Some industries become dramatically more productive over time. Computers get faster, factories become more automated and one agricultural worker can produce vastly more food than a century ago. But many government services remain labor intensive. A police officer can patrol only so many streets. A firefighter can respond to only one emergency at a time. A bus that once required a driver generally still requires one today.
Transit provides a particularly good example. Inflation-adjusted operating costs per trip rose 744% between 1947 and 2019.
As wages rise elsewhere in the economy, transit agencies, police departments, fire departments and other labor-intensive services must raise compensation to retain workers even though their productivity is not increasing at the same rate. Costs therefore rise faster than the price of goods and services offered by increasingly automated private businesses.
That creates a genuine fiscal challenge. But continually increasing sales-tax rates is not a sustainable solution.
The process increasingly resembles the proverbial boiling frog. No politician proposes taking a city from an 8% sales tax directly to 12%. Instead, voters are asked for half a percentage point for transit, another percentage point for public safety, perhaps another fraction for transportation or another worthy purpose a few years later. Each proposal comes with its own compelling list of needs. Voters are never asked where this process is supposed to end.
If 11.375% is acceptable, is 12%? How about 13%? Without a limiting principle, there is no obvious answer.
There are better alternatives.
First, governments need to attack Baumol’s Cost Disease by reducing the labor intensity of services wherever technology permits. Transit is an obvious candidate. Automated rail operations, better scheduling software, remote monitoring, predictive maintenance, modern fare systems and eventually autonomous buses can allow agencies to provide service with fewer labor hours. Contracting out services should also be considered when private providers can achieve greater productivity.
The objective should not be to preserve existing staffing models indefinitely and then raise taxes whenever labor costs outpace revenues. It should be to provide the greatest amount of service for each tax dollar.
Second, California should reconsider how local services are financed. Sales taxes are regressive. The Institute on Taxation and Economic Policy estimates that California’s lowest-income fifth pays 4.2% of its income in sales taxes, compared with just 0.4% for the top 1%.
If the state believes that certain local services require more public support, it would be fairer to provide some of that support through progressive state-level revenues rather than continually piling additional consumption taxes onto individual cities and counties.
State support should come with incentives for efficiency, and California would have to manage the volatility associated with its heavy reliance on high-income taxpayers. But these are manageable problems. Endless increases in local sales-tax rates are not.
Finally, the Legislature should make the 2% district-tax cap a real cap. If lawmakers believe 9.25% is too low, they should openly debate changing the statewide limit rather than continually creating exceptions for governments that have exhausted their existing taxing authority.
California voters value public safety, transportation and other public services. But government cannot answer every increase in the cost of providing those services with another “small” increase at the check stand.
Sooner or later, the sales-tax ratchet must stop.

- For Sales Tax Rates, How High is Too High? - September 14, 2026
- CA’s County Taxpayer Groups Are an Endangered Species – The Free Market Movement Should Save Them - June 14, 2026
- California Gets a Clean Audit – Now Comes the Hard Part - May 21, 2026
RELATED ARTICLES
-
 June 4, 2026
-
July 17, 2026
-
 August 18, 2021